October 14, 2022 key news items this week:
1. Axis, Alliances and the Martial Arts of Tai Chi: Every week we report news invariably linked to the Thucydides Trap, the unavoidable conflict between an emerging power and an established power.(Fig. 1)

. Just 3 days ago, the new PM of UK upgraded China as a threat rather than a systemic competitor. (Fig. 2).

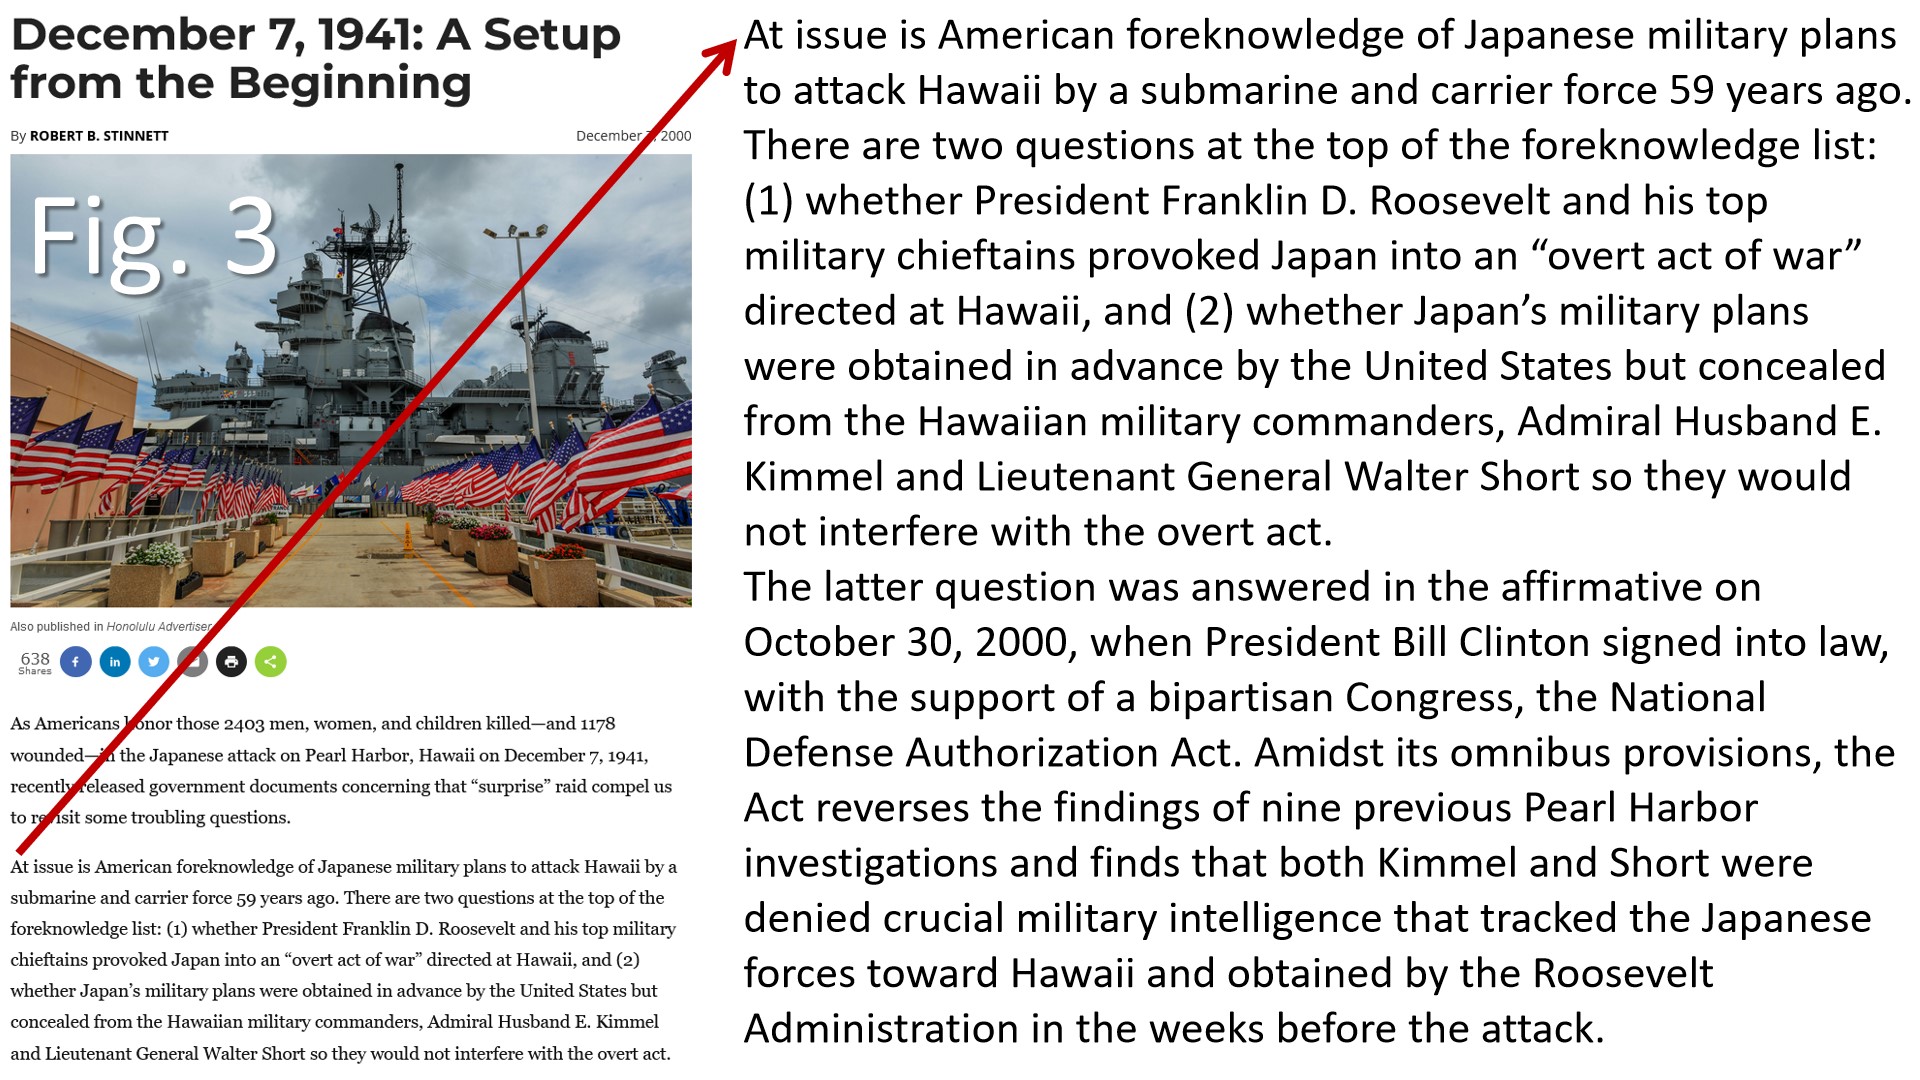
Did the perpetrator of the Opium War and the hundred year of humiliation of China seriously intend to win a war with her old adversary? By all counts, unlikely. Then, why the posturing when UK is facing more immediate threats like bankruptcy of her pension system, energy crisis, ongoing war of NATO and Russia? If we look back at history and patterns, King Edward II & King George V were instrumental to get WWI started between Germany and Russia (please read my earlier report for week ended on September 23, 2022) which culminated to WWII. But as devious as the planning went for UK, her status as a world power continued to decline after WWII. War is a game with no rules and in a complex network of axis and alliances, no single country or politicians can dictate the eventual outcome. Back in Asia, Japan attacked Pearl Harbour as a preventive action. Japan’s aim was to prevent the United States Pacific Fleet from interfering with its planned military actions in Southeast Asia against overseas territories of the United Kingdom, the Netherlands, and those of the United States. Why? The US cut off Japan’s lifeline of energy by an oil embargo. Therefore, Pearl Harbour was never an unprovoked surprised attack because US had foreknowledge yet President Roosevelt allowed the attack to succeed to give him a platform in 1941 to overcome the powerful America First non-interventionist movement. (Fig. 3)
(A memo dated October 7, 1940 by Lieutenant Commander Arthur McCollum, a U.S. Naval officer in the Office of Naval Intelligence (ONI) outlined eight provocations aimed at Japan. Its centerpiece was keeping the might of the U.S. Fleet based in the Territory of Hawaii as a lure for a Japanese attack ) (Fig. 4)

. Will the US chips embargo lure China to finally takeover Taiwan. Are we looking at the same playbook? I ventured to say no. China is a diligent student of history and her strategic policy of non alliance is designed to go around pitfalls of being dragged into unwarranted wars. China for its part has refused to walk into this trap, in recognition of the fact that fighting on an opponent's terms is a strategic defeat. China therefore uses the contact and friction with America to frame its alternative global solution to the challenge, perhaps in order to make America fight on Chinese terms. (Fig. 5).

So far, US has been forced to follow China’s BRI with a half baked $600 billion Public/Private Infrastructure Plan, a look-a-like Indo-Pacific Economic Framework against China’s RCEP, all long in rhetoric but short in substance. By November 9, the democrats would need to acknowledge her attempted encirclement of China has failed, after the Republicans got defeated of their Trade War against China just two years earlier.
2. Currency Wars: My friend posted a Twitter clip on our chat group which says”Long term UK-Gilt Bonds have posted a total return of -52.3% return since Dec. 2021. An entire decade’s gain wiped out”(Fig. 6).

As short term interest rates continue to spike higher and bond prices keep on falling, there is an outstanding $1 Trillion margin calls against UK Pension Funds because most Pension Funds have engaged leverage as a yield enhancement tool. (The mechanism on how it works is also found on Fig. 6). I have for many many years warned ZIRP and NIRP policies of the Central Banks whilst bailing out commercial banks from the sub-prime crisis of 2008 will eventually kill the Pension Funds and Insurance Companies. It is happening in the UK now but of course it is also happening in Europe, Japan and to a lesser extent in US. Does the Federal Reserve knows her interest rate hikes is doing very little to curb the energy crisis and supply chain shortage induced inflation. Do they know their policy is also wracking the long term financing structure globally? The answer to both question is yes. Then why? My speculation is for self preservation. Neither the White House, The US Treasury, the Federal Reserve nor the Pentagon can reverse the global de-dollarization trend. People in the know already understand QT can only happen for a short season because QE once prolonged cannot be stopped. Once the Fed restart QE, her last remaining credibility will be stripped and at the level of US National indebtedness, the dollar will go into an irreversible decline then collapse. The Fed is waiting for the whole world to beg for a restart of QE to justify what will be a logical outcome of a predestined end. The BOE took pains to explain their second QE was a short term temporary measure but they are just lying with eyes wide opened. How can BOE claim innocence of the Pension Funds leverage tools that involved Repo or the consequence of BOE ZIRP policies. In the US, liquidity of the Bond Market is measured by the MOVE Index, it has moved from Oct 2021 of 79 to the current level of 153. (Fig. 7)

. This is higher than the COVID locked down level of March 2020 and catching up to the 2008 Lehman crisis level. A 153 points on the MOVE Index implies a daily bond interest volatility of 9 basis points. At these volatility bond traders are simply unable to stomach the risks involved. Liquidity in the US Treasury market has dried up completely and with it the commercial credit market as well. We have reported for months that there is insufficient demand for US Treasuries because Foreign Holders, Insurers and Mutual Funds are all dumping. Two weeks ago, we stripped away the facade of the Reverse Repo Arrangement and show Banks have not only sold their entire Treasury Portfolio but in fact shorted some more. (Fig. 8)

is a graph published by the Federal Reserve and shows Federal Reserve’s Total Assets from end Dec 2020 to October 11, 2021. A nice graph showing a leveling off of Money Supply growth or QT. Sadly through, this picture is not true because FR has $2 trillion of Treasuries that she is committed to buy from Banks the next day. These Treasuries were temporarily off the FR books until midnight then it would come back on again. (Fig. 9)

is another FR Chart of the same period which shows FR Reverse Repo commitment of around zero in December 2020 to over $2 Trillion on October 11. When you put the two together, it then truly shows FR is printing money like there is no tomorrow. Why? The Administration have not slowed spending and there are few genuine buyers around. (Fig. 10)

Like BOE, ECB, BOJ, FR is the only buyer left of sovereign debt of their respective jurisdiction. Their economics of plunder, especially against the Chinese, the Russians and the Global South has failed. Like trapped rats, they will begin to devour their own and it won’t be a lovely scene.
3. Russian/Anglo American War in Ukraine: Two interesting pieces of news for readers who look at wars in terms of logistics.
(i) After scrapping the barrel to arm Ukraine, Germany has left with enough ammunition for barely two days of fighting (Fig. 11).

It is also unlikely Germany can step up production because of energy crisis.
(ii) US Army exhausts its ability to supply ammunition to Ukraine. (Fig. 12).

US stockpiles of certain equipment are “reaching the minimum levels necessary for war and training plans” and getting weapons stockpiles back to pre-invasion levels could take years, Mark Cancian wrote in a recent analysis. of the Center for Strategic and International Studies.
The past week’s financial markets:
A. Stock Market: Dow rose 338.04 points for the week (+1.15%) (Fig. 13)

. The market remained nervous and was hopeful for a Fed pivot. By Friday when CPI came out worse than expectation,Dow retracted 790 points from midweek peak of 30,424 to close at 29,634.
B. Debt Market: (Fig. 14):

USGG10YR ended the week at 4.022% an increase of 13.4 basis points or +3.44% change from the previous week. The market has repriced a 75 basis points increase for the next FOMC meeting. The entire yield curve moved up by 11 to 36 basis points in response to the worst than expected CPI numbers with steeper lift towards the short end. Yield inversion continued to be against commercial and mortgage lending.(Fig. 15)

C. FX Market (Fig.16):

for the week ended October 14, 2022, DXY opened at 112.747 and closed at 113.298 (Up +0.48%). The September quarter high of 144.7 has not been breached. GBP rebound sharply as the UK Chancellor of Exchequer was sacked to take the fall of a cabinet decision of tax reduction to be funded by increase borrowings. This gave rise to a further weakening of DXY to 112.3. Although the US CPI release on Friday should not have a serious impact, the finger print of the leveraged, HFT, algo trading CTA again appeared to pump up USD by shorting the Yen, oil and precious metals. (Fig. 17)

On the back of OPEC+ just reduced production to protect oil price, such derivative plays to suppress pricing on a tight physical market are counter intuitive and not sustainable.
D. Precious Metals & Crypto :(Fig. 18)

Gold price opened at $1693.7, and closed the week at $1643.7, a drop of $50 (-2.95%). Early in the week Hedge Funds further reduced their short positions with Central Banks and Sovereign Funds stepped up their purchases. CTA Funds begin to short on Wednesday as PPI showed inflation is still an issue and by Friday Gold shorts again in full swing. As regards Silver, CTA Funds had practically covered their remaining short position of 800 tons by Tuesday and then went on a fresh short of 1400 tons in the last 3 days of the week. Silver price dropped over 9% for the week. Shorting is not heavy for Bitcoin and price dropped just over 2%.(Fig. 19)

Ecclesiastes 1:2 "Vanity of vanities," says the Preacher; "Vanity of vanities, all is vanity." 3 What profit has a man from all his labor In which he toils under the sun? 4 One generation passes away, and another generation comes; But the earth abides forever. 5 The sun also rises, and the sun goes down, And hastens to the place where it arose.


